Independent Financial Advisory

Commercial Credit & Capital Advisory

The lender’s perspective. The borrower’s priorities.

Commercial financing decisions require more than access to capital. They require an understanding of how lenders evaluate risk, structure credit, negotiate terms, and respond to changing financial circumstances.

With more than two decades of commercial banking experience followed by senior corporate financial leadership, Ryan Toncheff brings both perspectives to complex commercial financing situations.

From evaluating existing debt portfolios to sourcing new credit facilities, preparing financing transactions, and navigating challenging lender relationships, Ryan provides practical financial guidance informed by firsthand experience on both sides of the lending relationship.

Commercial Financing Expertise

Commercial & Industrial and Commercial Real Estate Financing

Independent, borrower-side advisory services across the full spectrum of commercial lending, including Commercial & Industrial (C&I) credit facilities and Commercial Real Estate (CRE) financing.

Services encompass evaluating existing financing arrangements, assessing borrowing capacity, sourcing capital, structuring transactions, reviewing proposed terms, and supporting lender negotiations.

Commercial & Industrial (C&I) Financing (13 structures)
  • Revolving lines of credit and working capital facilities
  • Commercial term loans
  • Asset-based lending (ABL)
  • Accounts receivable and inventory financing
  • Borrowing-base facilities
  • Equipment financing and capital expenditure loans
  • Acquisition and business expansion financing
  • Owner-occupied commercial real estate financing
  • Secured and unsecured commercial credit facilities
  • Cash-flow-based lending
  • Senior and subordinated debt
  • Private credit and alternative lending arrangements
  • Multi-entity and cross-collateralized financing structures
Commercial Real Estate (CRE) Financing (16 structures)
  • Commercial real estate acquisition financing
  • Construction and development loans
  • Land acquisition and development financing
  • Bridge and transitional financing
  • Permanent commercial mortgages
  • Multifamily and mixed-use properties
  • Industrial and warehouse properties
  • Office and retail properties
  • Hospitality and specialized commercial properties
  • Income-producing investment properties
  • Owner-occupied commercial properties
  • Commercial real estate portfolio financing
  • Cross-collateralized real estate facilities
  • CRE refinancing and recapitalization
  • Construction-to-permanent financing
  • Maturity extensions and loan modifications

Commercial financing is not a one-size-fits-all process.

Different credit structures carry distinct underwriting requirements, collateral considerations, financial covenants, repayment obligations, and lender expectations.

Effective financing advisory requires understanding both the lender’s credit framework and the borrower’s operational, financial, and strategic objectives. Ryan Toncheff’s experience across commercial banking, corporate financial leadership, and capital advisory is the foundation for evaluating these financing alternatives. No financing approval, availability, or lender outcome is guaranteed.

Related reading: the book Commercial Credit Intelligence.

Request Financing Advisory

Please do not include loan documents or confidential files in the initial inquiry.

Pre-Commitment Advisory

Commercial Loan Term Sheet Review & Negotiation

Before You Sign the Term Sheet, Know What You’re Negotiating.

A financing structure can be good for the bank without being optimal for the borrower.

Commercial loan term sheets establish the foundation for financing relationships, often defining economic terms, financial covenants, collateral requirements, guarantees, reporting obligations, and operational restrictions.

These provisions can have significant consequences for a borrower’s liquidity, financial flexibility, and future financing alternatives.

With more than 20 years of commercial banking experience, combined with senior corporate financial leadership and capital advisory experience, Ryan Toncheff brings an informed perspective from both sides of the lending relationship.

Understanding how lenders evaluate, structure, price, and approve commercial credit provides an advantage when assessing proposed financing terms and identifying opportunities for negotiation.

For the framework behind this approach, see the book Commercial Credit Intelligence.

Services include

  • Loan Pricing & EconomicsInterest rates, spreads, floors, fees, amortization, and prepayment provisions.
  • Financial Covenant AnalysisLeverage, debt service coverage, liquidity, net worth, and covenant headroom.
  • Collateral & GuaranteesSecurity requirements, borrowing bases, cross-collateralization, and guarantor exposure.
  • Loan StructureMaturity, repayment schedules, revolving availability, renewal provisions, and extension options.
  • Operating RestrictionsDistribution limitations, additional indebtedness, acquisitions, capital expenditures, and other restrictive covenants.
  • Default & Cure ProvisionsFinancial implications of default triggers, cure periods, and cross-default provisions.
  • Competing Term Sheet AnalysisSide-by-side evaluation of financing proposals based on total cost, structure, flexibility, and risk.
  • Borrower-Side NegotiationIdentify unfavorable terms, develop alternative structures, and support negotiations with lenders.

Pre-Commitment Credit Review

An independent assessment of a proposed commercial financing arrangement before the borrower executes a term sheet or commitment letter.

Potential deliverables

  • Written term sheet assessment
  • Financing economics and covenant analysis
  • Identification of material borrower-side risks
  • Recommended negotiation points
  • Alternative financing structures where appropriate
  • Lender negotiation support

The time to evaluate a financing structure is before committing to it.

A lender’s initial proposal reflects its underwriting standards, credit policies, and risk considerations. Borrowers must also evaluate whether those terms support their operational needs, liquidity requirements, and long-term financial objectives.

The objective is not to create an adversarial lending relationship. It is to identify a commercially reasonable structure that appropriately balances lender protections with borrower flexibility.

This is a commercial and financial assessment, not legal review; legal review of term sheets and loan documents should be performed by qualified counsel. No financing approval or improved terms are guaranteed.

Have a Commercial Loan Term Sheet Under Review?

Obtain an independent borrower-side assessment before committing to the proposed financing structure.

Please do not send the term sheet or other documents with the initial inquiry; none are accepted.

Request a Term Sheet Review

Background

Experience Across Both Sides of the Credit Relationship

Ryan Toncheff’s commercial credit experience spans more than two decades in commercial banking, including middle-market lending, credit analysis, portfolio management, relationship management, and complex financing arrangements.

His banking career included positions with Wells Fargo, Bank of America, and California Bank & Trust. He subsequently transitioned into senior corporate financial leadership, including serving as Chief Financial Officer of a substantial real estate development and construction enterprise.

Ryan understands how commercial lenders evaluate creditworthiness, structure financing facilities, assess collateral, measure repayment capacity, negotiate covenants, and manage troubled credits. He also understands the practical challenges businesses face when managing liquidity, refinancing obligations, lender expectations, and competing capital requirements.

The result is advisory work informed by the lender’s underwriting discipline and the borrower’s operational realities.

Read Ryan Toncheff’s professional biography

Advisory Capabilities

Eight areas of commercial credit and capital advisory

01

Commercial Debt Portfolio Assessment

Understand Your Entire Debt Position

Evaluate existing commercial financing arrangements to develop a consolidated understanding of debt obligations, structural risks, and financing opportunities.

Capabilities include

  • Enterprise debt stack assessments
  • Commercial loan portfolio reviews
  • Credit facility analysis
  • Loan maturity and refinancing schedules
  • Interest rate exposure
  • Collateral and guaranty structures
  • Borrowing availability
  • Debt service requirements
  • Financial covenant obligations
  • Capital structure optimization

Deliverable: a comprehensive assessment identifying financing risks, opportunities, and potential strategic alternatives.
02

Commercial Loan Sourcing & Financing Strategy

Identify the Right Capital for the Right Purpose

Assist businesses in evaluating commercial financing alternatives and preparing financing strategies aligned with their financial objectives. Services may include identifying prospective lenders, coordinating financing discussions, evaluating proposals, and supporting negotiations.

Capabilities include

  • Commercial bank financing
  • Working capital facilities
  • Revolving lines of credit
  • Asset-based lending
  • Commercial real estate financing
  • Construction and development financing
  • Equipment financing
  • Acquisition financing
  • Private credit alternatives
  • Refinancing and recapitalization strategies

No financing approval, lender commitment, or particular outcome is promised or implied.

03

Credit Pre-Underwriting & Lender Qualification

Know How a Lender May Evaluate Your Business Before You Apply

One of Ryan’s distinguishing capabilities is assessing financing opportunities from the perspective of an experienced commercial banker. Businesses can engage Ryan to evaluate their financial position before approaching prospective lenders. A disciplined pre-underwriting assessment can help identify potential credit weaknesses, anticipate lender questions, and approach financing discussions with greater preparation.

Capabilities include

  • Historical financial statement analysis
  • EBITDA and cash flow normalization
  • Debt service coverage analysis
  • Leverage and capitalization analysis
  • Liquidity assessment
  • Borrowing-base analysis
  • Collateral evaluation
  • Guarantor financial analysis
  • Credit risk identification
  • Financial covenant projections
  • Preliminary financing capacity assessment
  • Lender readiness recommendations

Pre-underwriting is an independent advisory assessment. It is not a lender’s credit decision or a financing commitment.

04

Debt Capital Raising & Financing Memorandums

Present Your Financing Opportunity With Institutional Discipline

Assist businesses in preparing professional financing materials that communicate financial position, operating performance, financing requirements, and repayment capacity. Ryan approaches these materials as someone who has evaluated commercial credit transactions inside financial institutions; the objective is to organize financial information around the questions lenders are likely to ask.

Capabilities include

  • Confidential Information Memorandums (CIMs)
  • Debt financing memorandums
  • Lender presentation materials
  • Executive transaction summaries
  • Historical financial analysis
  • Financial projections
  • Sources and uses of funds
  • Debt capacity assessments
  • Capital structure analysis
  • Transaction financial modeling
  • Supporting credit documentation
  • Lender due diligence preparation

05

Lender Advocacy & Relationship Management

Navigate Lender Relationships With Confidence

Independent support for businesses managing commercial banking relationships and significant credit obligations, informed by an understanding of both institutional lender expectations and borrower objectives.

Capabilities include

  • Lender communication strategy
  • Annual credit reviews
  • Loan renewal preparation
  • Financial reporting coordination
  • Covenant negotiations
  • Credit agreement amendments
  • Waiver requests
  • Refinancing discussions
  • Collateral release requests
  • Guaranty negotiations
  • Credit relationship transitions
  • Multi-lender coordination

06

Financial Covenant & Compliance Advisory

Stay Ahead of Your Credit Obligations

Assist businesses in understanding and managing financial covenant requirements and lender reporting responsibilities.

Capabilities include

  • Financial covenant identification
  • Covenant calculation review
  • Compliance certificate preparation support
  • Financial reporting calendars
  • Covenant forecasting
  • Headroom analysis
  • Default risk assessment
  • Reporting process improvements
  • Credit agreement interpretation coordination
  • Covenant amendment strategies

This is financial advisory, not legal interpretation. Questions of legal meaning or enforceability belong with qualified counsel.

07

Distressed Credit & Financial Restructuring

Experienced Guidance When Financing Becomes Challenging

Support for businesses experiencing financial pressure, lender concerns, covenant deterioration, or refinancing uncertainty. Difficult financing situations require disciplined analysis, credible communication, and an understanding of how lenders approach credit deterioration. Ryan’s experience in commercial banking and corporate financial leadership provides a practical foundation for evaluating these situations and developing actionable alternatives.

Capabilities include

  • Distressed credit assessments
  • Liquidity stabilization planning
  • Covenant default analysis
  • Lender workout strategy
  • Forbearance discussions
  • Debt restructuring alternatives
  • Refinancing assessments
  • Collateral and guaranty exposure analysis
  • Cash flow forecasting
  • Creditor communication planning
  • Financial turnaround support

08

Capital Structure & Strategic Financial Advisory

Align Financing Decisions With Enterprise Strategy

Assist businesses in evaluating how debt financing affects liquidity, financial flexibility, enterprise value, and long-term strategic objectives.

Capabilities include

  • Capital structure reviews
  • Debt capacity analysis
  • Financing alternatives
  • Acquisition financing
  • Recapitalization planning
  • Financial scenario modeling
  • Enterprise liquidity strategy
  • Debt maturity management
  • Capital allocation considerations
  • Strategic refinancing decisions

Debt Maturity & Refinancing Risk Analysis

Understand Your Refinancing Exposure Before It Becomes a Liquidity Problem.

Debt maturity risk is often underestimated when individual credit facilities are evaluated independently.

Across multiple loans, lending institutions, and legal entities, approaching maturities can create concentrated refinancing requirements, liquidity pressures, collateral constraints, and potential covenant complications.

Independent analysis of commercial debt maturities and refinancing exposure across individual facilities and enterprise-wide debt portfolios complements the commercial debt portfolio assessment and capital structure advisory services above.

  1. 01Debt Maturity Ladder Analysis

    Develop a consolidated schedule of contractual maturities across commercial credit facilities, including revolving lines, term loans, equipment financing, and CRE debt.

    Identify maturity concentrations, balloon payments, scheduled principal reductions, and refinancing requirements.

  2. 02Refinancing Feasibility Assessment

    Evaluate whether existing financing arrangements are likely to satisfy anticipated lender underwriting requirements at renewal or maturity.

    Analyze cash flow, leverage, debt service coverage, collateral support, borrowing capacity, and financial covenant compliance.

  3. 03Liquidity & Balloon Payment Exposure

    Assess upcoming principal obligations against available liquidity, operating cash flow, borrowing availability, and anticipated capital requirements.

    Identify potential funding gaps and evaluate alternative financing strategies.

  4. 04Interest Rate Reset & Repricing Risk

    Evaluate floating-rate exposure, interest-rate resets, expiring fixed-rate periods, and the potential effects of refinancing at prevailing market rates.

    Assess implications for debt service, cash flow, covenant headroom, and financial flexibility.

  5. 05Lender Renewal & Extension Risk

    Review renewal provisions, extension options, lender approval requirements, covenant conditions, and anticipated underwriting considerations.

    Identify situations requiring early lender engagement or alternative financing arrangements.

  6. 06Collateral & Capital Structure Constraints

    Evaluate collateral availability, existing liens, guarantees, cross-default provisions, cross-collateralization, and contractual restrictions that may affect refinancing alternatives.

  7. 07Multi-Entity & Enterprise-Wide Refinancing Exposure

    Analyze how debt maturities across subsidiaries, affiliated entities, and holding companies interact with centralized cash management, intercompany funding arrangements, and enterprise-wide liquidity requirements.

  8. 08Refinancing Strategy & Execution Support

    Develop refinancing alternatives, evaluate prospective lenders, prepare lender-ready financial information, and support negotiations involving renewals, extensions, modifications, and replacement financing.

Potential Engagement Deliverables

  • Consolidated debt maturity schedule
  • Enterprise-wide maturity ladder
  • Refinancing risk assessment
  • Liquidity gap and funding requirements analysis
  • Covenant and borrowing-capacity evaluation
  • Interest-rate sensitivity analysis
  • Refinancing alternatives and lender strategy
  • Recommended financing action plan

Refinancing risk should be managed before maturity, not when repayment becomes imminent.

A coordinated approach to debt maturity analysis allows businesses to anticipate financing requirements, evaluate alternatives, engage lenders proactively, and preserve financial flexibility.

This is commercial and financial assessment, not legal review; interpretation of covenants, default provisions, and credit agreements belongs with qualified counsel. No financing availability, approval, or lender outcome is guaranteed.

See the framework in the book Commercial Credit Intelligence.

Request a Maturity Analysis

Please do not include loan documents or confidential files in the initial inquiry.

Direct Engagements

Selective Engagements. Direct Expertise.

Ryan’s principal professional commitments are through Perrin & Co., where he serves as Partner, Perrin & Co., LLC.

Alongside those responsibilities, he selectively undertakes independent advisory engagements with businesses facing financing decisions, complex credit situations, or strategic capital challenges that benefit from his direct involvement.

These engagements are intentionally limited and generally involve circumstances where his commercial banking background, financial leadership experience, and personal attention can provide meaningful value.

Rather than operating a high-volume consulting practice, Ryan approaches these opportunities individually, evaluating the nature of the assignment, the financial circumstances involved, and the potential contribution he can make.

“Some financing decisions warrant more than a conventional advisory process. They warrant experienced judgment, direct involvement, and an understanding of how credit decisions are actually made.”

Direct engagements are considered on a selective basis, subject to availability, professional obligations, and the specific requirements of the assignment. Prospective clients are encouraged to provide a brief overview of their financing situation for consideration.

Request a Confidential Consultation

Ideal Engagements

When Direct Advisory May Be Appropriate

  • Preparing for a Significant Financing Transaction

    A business considering a new credit facility, acquisition financing, or substantial refinancing.

  • Evaluating an Existing Debt Portfolio

    An organization seeking an independent assessment of financing obligations, covenant exposure, or capital structure.

  • Navigating a Difficult Lender Relationship

    A business experiencing challenges involving credit renewals, covenant compliance, lender negotiations, or restructuring.

  • Preparing for Institutional Credit Review

    A company seeking to understand how lenders may evaluate its financial performance, repayment capacity, and financing request.

  • Raising Debt Capital

    An organization requiring a professionally prepared financing memorandum, lender presentation, or coordinated debt financing process.

  • Managing Complex Multi-Entity Financing

    A business with multiple borrowing entities, credit facilities, collateral arrangements, and lender relationships.

Books & Research

Published Perspectives on Commercial Credit

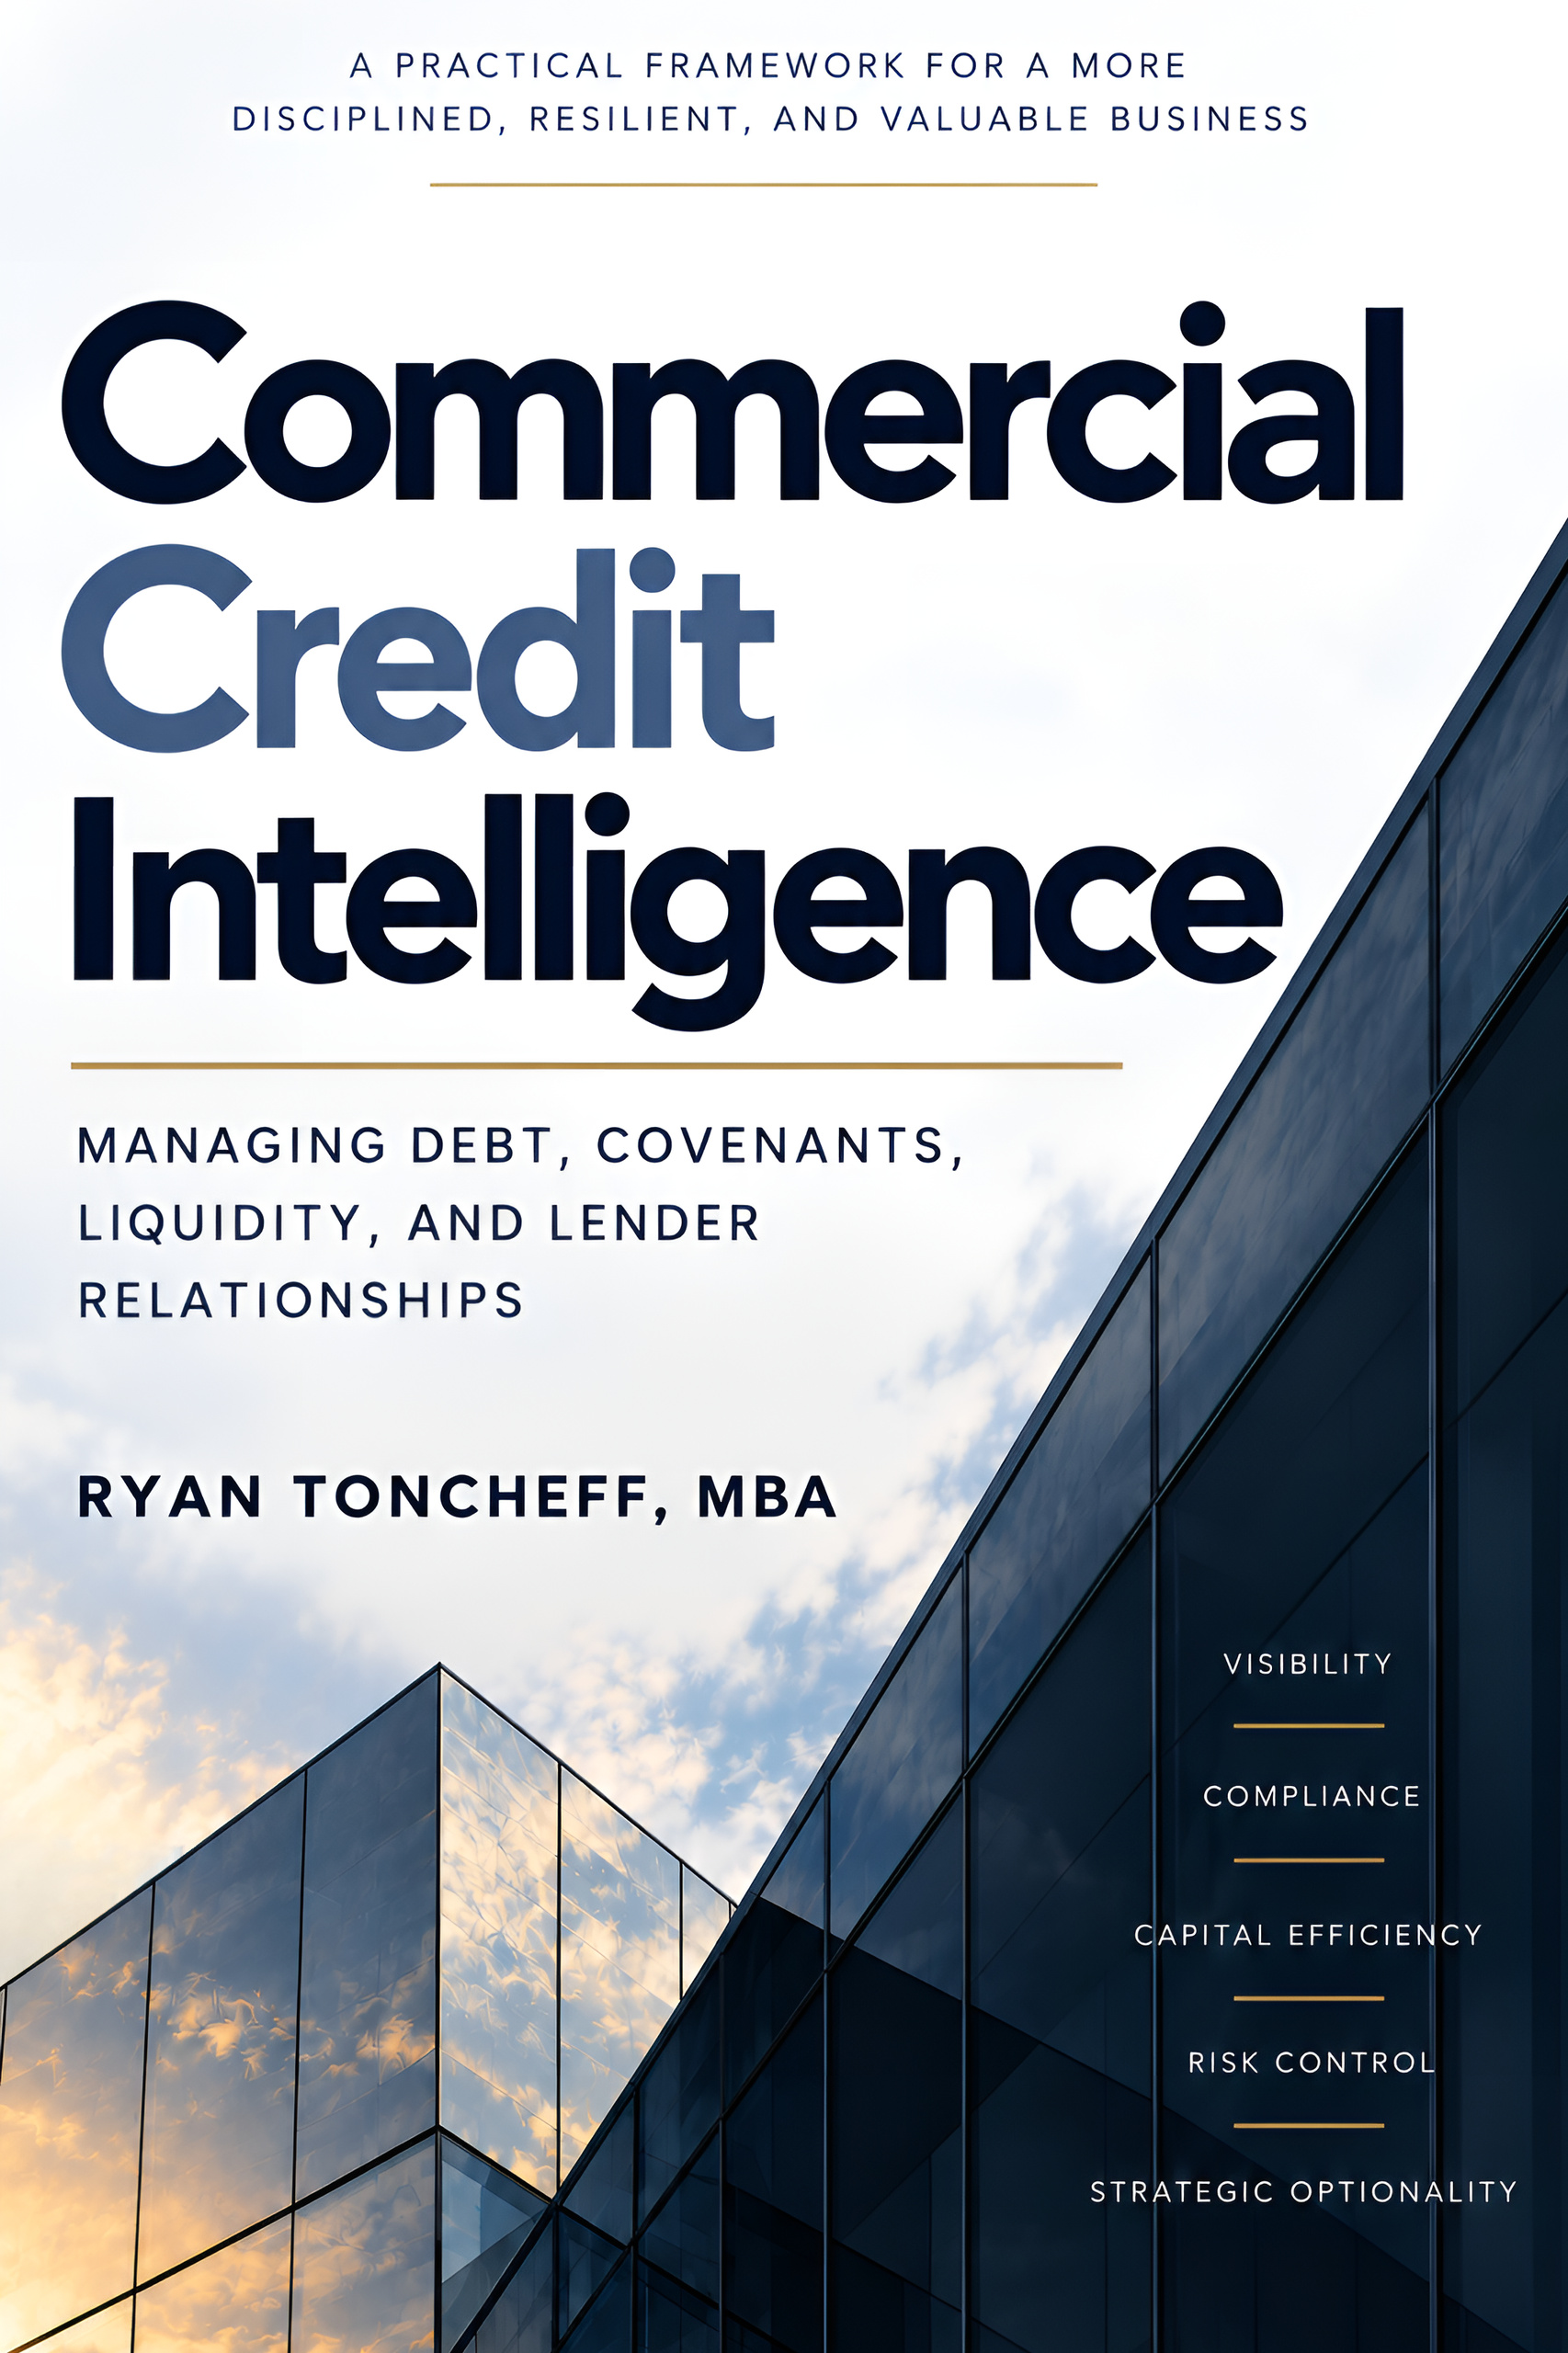
Cover of Commercial Credit Intelligence by Ryan Toncheff

Commercial Credit Intelligence

Managing Debt, Covenants, Liquidity, and Lender Relationships

Ryan’s book, Commercial Credit Intelligence, examines the principles underlying disciplined commercial debt management, including financial covenant compliance, liquidity, lender relationships, credit risk, and enterprise debt portfolio oversight. The publication reflects many of the same analytical disciplines that inform his commercial credit advisory work.

About the book

Research

Commercial Credit Intelligence: A Framework for Enterprise Debt Portfolio Management

Available through SSRN and MPRA.

Confidential Inquiry

Discuss a Financing Challenge

Businesses seeking independent guidance on commercial credit, financing strategy, lender relationships, or complex debt obligations may submit a confidential inquiry for consideration.

Direct advisory engagements are accepted selectively based on the nature of the assignment, professional availability, and potential fit.

Please do not include financial statements, tax returns, bank credentials, or loan documents in this initial inquiry, and no attachments are accepted. A brief overview is sufficient. Information submitted is handled as described in the privacy policy. Submitting an inquiry does not create an advisory relationship.